

Are There Bad-Credit Ford Auto Loans Available Near Chesterfield, Missouri?
Yes. Drivers with damaged, thin, or rebuilding credit can still find Ford auto loans near Chesterfield, Missouri, though the interest rate usually reflects the lender's risk. Suntrup Ford Westport, about 15 miles east of Chesterfield on I-64/Hwy 40, arranges financing through the manufacturer's lender, local Missouri banks, and national lenders, and its finance department says it has programs for buyers who've been turned down before. Approval isn't guaranteed, and rates vary widely by credit tier: Experian's Q2 2026 data shows subprime borrowers (scores 501–600) averaged 19.10% APR on used vehicles, compared with 8.81% for prime borrowers. A down payment, a realistic budget, and comparing offers can make a real difference. Learn more in our guide to Ford financing options for all credit near St. Louis.
- Bad credit isn't an automatic no. Lenders also weigh income, job history, existing debt, and the size of your down payment.
- Your tier changes the cost. Average used-car APR was 8.81% for prime and 19.10% for subprime borrowers in Q2 2026 (Experian).
- Rate shopping is protected. FICO counts multiple auto loan inquiries within a 14- or 45-day window as one, depending on the score version.
- Chapter 13 needs court permission. In an open Chapter 13 case, you generally need the bankruptcy court's approval before taking on a car loan.
- Add-ons are optional. The CFPB notes that extended warranties, GAP, and credit insurance aren't required and their prices are negotiable.
- Check your reports for free. All three credit bureaus offer free weekly credit reports at AnnualCreditReport.com.
If you've been turned down for a car loan, or you're dreading that conversation, you're far from alone. A job loss, medical bills, a divorce, or a bankruptcy can weigh on a credit score for years, even after your finances have settled down. For drivers in Chesterfield Valley, along Clarkson Road, and across West County, our Ford dealership serving Chesterfield is a short drive away, and the Suntrup Ford Westport finance department works with buyers whose credit is excellent, fair, or still on the mend. This guide explains how bad-credit auto lending works in 2026, what lenders look at, and how to walk in prepared at a no-pressure Ford dealer near Chesterfield.
What Your Credit Tier Means for a Ford Auto Loan in 2026
Lenders group borrowers into credit tiers, and each tier tends to see a different average rate. The table below shows Experian's latest averages, plus what those rates could mean for the monthly payment on a $25,000 used-vehicle loan.
| Credit Tier | Score Range | Avg. New-Vehicle APR | Avg. Used-Vehicle APR | Est. Payment, $25,000 Used Loan (60 Months) |
|---|---|---|---|---|
| Super prime | 781–850 | 4.41% | 6.29% | About $487/month |
| Prime | 661–780 | 6.15% | 8.81% | About $517/month |
| Near prime | 601–660 | 9.71% | 13.93% | About $581/month |
| Subprime | 501–600 | 13.52% | 19.10% | About $650/month |
| Deep subprime | 300–500 | 16.11% | 21.62% | About $685/month |
APR averages from Experian (published September 2026). Payment estimates are our calculations using each tier's average used-vehicle APR, $25,000 financed, and a 60-month term. They exclude taxes, fees, and add-ons and are not loan offers.
On that same $25,000 loan, the gap between the prime and subprime averages works out to roughly $133 more per month and about $8,000 more in interest over five years. That's why even a modest score improvement, a larger down payment, or a less expensive vehicle can pay off.
What Lenders Look at Besides Your Credit Score
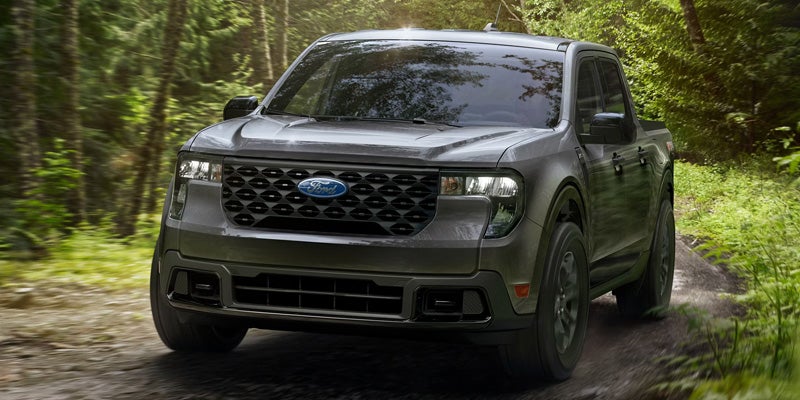
Choosing a vehicle that fits your budget, whether a compact Maverick pickup or a used model, helps keep the amount you finance under control.
Your score opens the conversation, but it isn't the whole application. Auto lenders commonly look at how steady your income is, how long you've been at your job and address, how much of your monthly income already goes to debt, how much you're putting down, and how the loan amount compares with the vehicle's value. Recent on-time payments can also help show that a rough stretch is behind you. Browsing used vehicles in our St. Louis inventory with a price range in mind makes it easier to find a loan amount a lender is comfortable with.
Credit Situations Lenders May Still Consider
According to Suntrup Ford Westport's finance pages, the dealership works with lenders that have programs for buyers coming out of Chapter 7 or Chapter 13 bankruptcy, buyers with a prior repossession, and buyers who've been declined elsewhere. If your challenge is a short credit history rather than a bad one, our guide for the best Ford dealer for first-time buyers covers how a thin credit file is handled.
What to Bring to Your Finance Appointment
Every lender sets its own requirements, but they commonly ask for a valid driver's license, recent pay stubs or other proof of income, proof of residence such as a utility bill, and auto insurance details. If you're trading in a vehicle, bring its title or loan payoff information. If you're in an open Chapter 13 case, bring a copy of the court order allowing you to take on the new loan.
How to Strengthen a Bad-Credit Auto Loan Application
- Check your credit reports first. Equifax, Experian, and TransUnion offer free weekly reports at AnnualCreditReport.com, so you can spot and dispute errors before a lender sees them.
- Know your budget before you shop. Our What's My Buying Power tool helps you set a realistic price range before you start comparing vehicles.
- Put more money down. Every dollar down reduces the amount financed. If you have a vehicle now, estimate your trade-in value to see how much it could contribute.
- Run the payment math. Try different rates and terms in our Ford payment calculator. The CFPB notes that a longer term lowers the monthly payment but raises the total interest you pay.
- Right-size the vehicle. Shopping used vehicles under $15K or used Ford Explorers under $25,000 near Chesterfield can keep the loan amount within reach.
- Compare offers in a short window. FICO treats multiple auto loan inquiries within a 14- or 45-day period as one inquiry, depending on the score version. Getting a quote from your bank or credit union gives you a rate to compare.
- Read every line before you sign. Ask to see the APR, the loan term, and the total of payments. Add-ons like GAP or an extended warranty are optional, and you can say no.
Bad-Credit Ford Auto Loan Questions, Answered
Are there bad-credit Ford auto loans available near Chesterfield, Missouri?
Yes. Suntrup Ford Westport, about 15 miles east of Chesterfield on I-64/Hwy 40, arranges financing through the manufacturer's lender, local Missouri banks, and national lenders, including programs for buyers who've been turned down before. Approval and rates depend on each lender's review of your credit, income, and down payment.
What credit score do I need to get approved for a car loan?
There's no single minimum, because each lender sets its own criteria. Experian's Q2 2026 data includes loans to borrowers in every tier, down to deep subprime (scores 300–500), where the average used-vehicle APR was 21.62%. A lower score usually means a higher rate rather than an automatic denial.
Will applying with several auto lenders hurt my credit score?
Less than you might think. FICO counts multiple auto loan inquiries made within a 14-day window (older score versions) or a 45-day window (newer versions) as a single inquiry, so keep your loan shopping within a couple of weeks to be safe.
Can I get a car loan after bankruptcy in Missouri?
Often, yes. After a Chapter 7 discharge, some lenders specialize in post-bankruptcy auto loans. During an open Chapter 13 case, you generally need the bankruptcy court's permission to take on new debt. In the Eastern District of Missouri, which includes St. Louis County, that usually means your attorney files a motion showing the loan amount, the payment, and why you need the vehicle.
Should I use a co-signer to get a better rate?
A co-signer with stronger credit may help you qualify or lower your rate, but the CFPB warns that a co-signer is equally responsible for repaying the loan. If payments are missed, the lender can collect from the co-signer, and the late payments can lower the co-signer's credit scores too.
Do I have to buy GAP insurance or an extended warranty to get approved?
No. The CFPB lists extended warranties, GAP coverage, and credit insurance as optional add-ons whose prices are negotiable. Some buyers choose them for protection, but they add to your total cost, so make sure any product you agree to is one you want.
Start With a Conversation, Not a Judgment
Tell us where your credit stands today. Our finance team will walk you through realistic options for your next Ford.
APR figures are national averages from Experian data as of Q2 2026 and are not offers of credit. Payment examples are estimates that exclude taxes, title, license, fees, and optional products. All financing is subject to lender approval, and approval is not guaranteed. Rates and terms depend on credit history, income, down payment, vehicle, and lender. This page is general information, not financial or legal advice; consult a qualified professional about bankruptcy or credit questions. Confirm current financing options with Suntrup Ford Westport, 2020 Kratky Road, Saint Louis, MO 63114, Sales: (314) 697-1796.